It’s National Financial Literacy Month (FLM), where the Financial Consumer Agency of Canada (FCAC) helps equip Canadians with practical tools and tips to manage their money in a changing world. Throughout November, the FCAC is discussing the ever-changing financial marketplace and the importance of checking up on financial health.
At Magenta, our purpose is to connect people with opportunities to build a better tomorrow. This month, we’re furthering that purpose by supporting National Financial Literacy Month and sharing resources dedicated to helping Canadians:
- manage their money and debt wisely;
- save for the future; and
- understand their financial rights.
This year’s Financial Literacy Month campaign encourages Canadians to have purposeful conversations about money and financial moments that can help them feel more confident and increase their well-being. As brokers and investment agents, you have an important role to play in facilitating these conversations and in normalizing financial planning. Talking about money is an important first step toward building financial confidence and navigating an increasingly complex financial marketplace. So, we decided to take things a step further: We had a talk with our money. And it turns out, the denizens of our wallets were dying to speak.
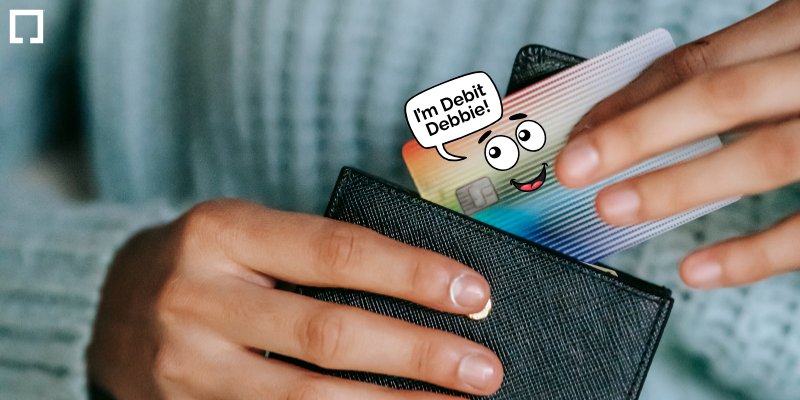
Debit Debbie: On Making a Budget
“Many kids these days don’t know how to budget. My brother Credit Carlos talks a big game about treating you to the high life, but when the bill comes, he always makes his date pay. Me? I tell it like it is. There’s no pretending that it doesn’t count because you don’t have to pay it back until later. That’s why budgeting is so important. When your clients sit down and figure out how much they earn, spend, and save, they can set realistic limits. They can differentiate between what they need- a place to live, food to eat, health expenses- and what they want- a tropical vacation, the latest tech, or a subscription service that they will absolutely use, for sure. The FCAC has a great step-by-step tool to guide them through planning a budget. The best part? It’s absolutely free!”
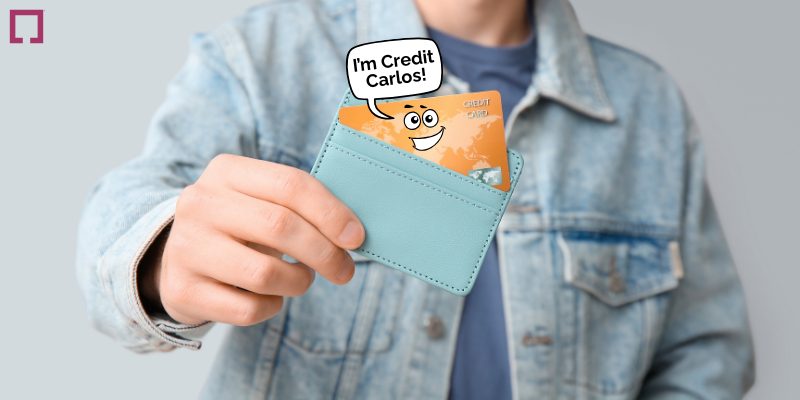
Credit Carlos: On Managing Debt
“Ok, ok, she doesn’t have to be rude, but Debit Debbie has a point about avoiding debt. I might have enabled some of your clients…less-advisable shopping sprees. I’m sorry, really, I am. To prove it, here’s a little something to help you manage some of the debt I’ve caused you. First, take Debbie’s guidance: budget. To start, list your clients’ debts in order, from the highest interest rate to the lowest. Consider putting money towards the debt with the highest interest rate. The sooner they resolve their high-interest debts, the easier it will be to save for the rest. Debt consolidation is a technique in which one exchanges two or more smaller loans for a single larger one. By acquiring a long-term loan, such as a mortgage, your clients may gain the financial power to pay off their smaller loans. A mortgage can help them streamline their records, make it easier to budget and plan; have a lower interest rate than the average of their previous smaller debts; and lower their interest fees and monthly payments in the long run.”
Giving Geoffrey: On Knowing Your Incentives
“Wow, you can see me? Like your other incentives, I figured you must have forgotten I was here. You go to Tim Hortons all the time but never use me, your gift card! That’s a missed opportunity; us gift cards are only good for specific stores, you know. The incentives your clients get for being a Canadian are a lot like me: lots of consumers don’t take full advantage. They can contribute $7,000 every year to their Tax-Free Savings Account (TFSA) and use it to hold investments, for which the dividends they earn are tax-free. A First Home Savings Account (FHSA) lets you do the same, with an annual contribution limit of $8,000 and a maximum of $40,000, with the caveat that the money can only be withdrawn to purchase your first home. There are other kinds of accounts for special purposes that are tax-free until withdrawal, like Registered Retirement Savings Plans (RRSPs) and Registered Education Savings Plans (RESPs), too. By saving money in these kinds of accounts, you can maximize the income you eventually receive from interest and dividends.”
That’s all for this week! Come back on November 27th as we continue to explore the “Talk Money” theme for Financial Literacy Month.
Disclaimer
The opinions and viewpoints presented in this document are exclusively those of the several writers and do not represent the perspectives of any associated individuals or organizations, including but not limited to the writers’ current or former employers. This article serves purely informational purposes, and the writers have made efforts to verify the accuracy of the information and analysis. The writers take full responsibility for any opinions, forecasts, or predictions made. They do not guarantee the precision or completeness of the document’s contents. This document does not offer professional or investment advice. The writers will not be liable for any consequences resulting from reliance on this piece. Readers should consult with a certified expert before making any financial decisions.